A stolen mower, a rock through a client’s window, a trailer cleaned out between jobs — when something goes wrong, the first thing you need to know is whether your policy actually covers it. For most lawn care pros, the answer comes down to carrying two kinds of coverage, not one. Here’s how they split the work.
TL;DR: General liability insurance covers accidents and injuries you cause to other people or their property, while trailer and equipment (inland marine) insurance covers your own tools and gear if they're stolen or damaged. Most lawn care pros need both!
General liability starts at $33.75/month ($375/year), and equipment coverage is a small add-on starting around $13/month, depending on how much gear you’re insuring.
How General Liability Insurance Works for Lawn Pros
Think of general liability insurance as your “oops” coverage. If your lawn care business accidentally causes damage or injury to a third party, general liability helps cover the cost.
It typically covers:
- Damage to someone else’s property — like accidentally knocking over a client’s garden statue
- Injuries to customers or bystanders — like if someone trips over your equipment on the job site
- Legal defense costs if you get sued — like lawyer fees and settlements tied to common lawn care claims
It doesn’t cover:
- Your tools, trailer, or machines
- Lawn care injuries sustained by you or your employees (that’s what workers comp is for)
- Accidents involving ladders or off-the-ground work, like large tree trimming
How Trailer and Equipment Insurance Works for Lawn Pros
Trailer and equipment insurance protects the mobile tools that keep your lawn care business moving. If your gear is ever stolen, damaged, or destroyed, this coverage helps you avoid paying out of pocket for repairs or replacements.
It typically covers:
- Utility trailers (must be detached to qualify for coverage)
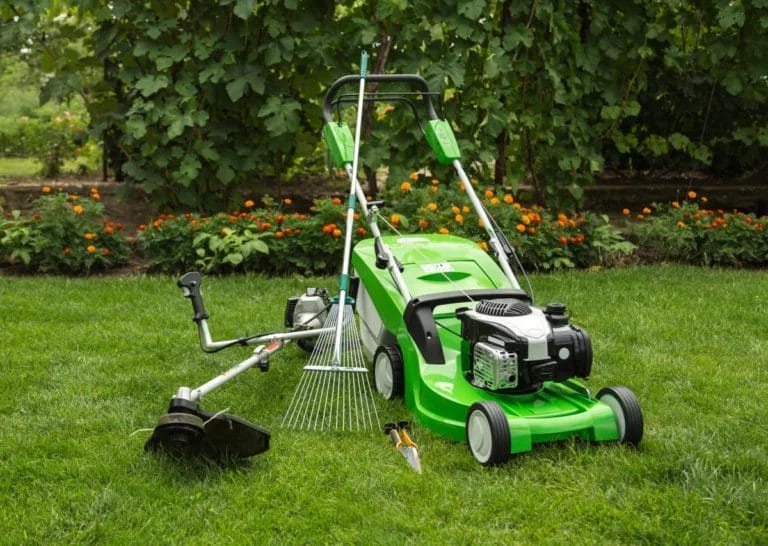
- Lawn mowers (push, riding, and zero-turn)
- Lawn feed and fertilizer spreaders
- Weed eaters, leaf blowers, hedge trimmers, aerators, and more
It doesn’t cover:
- Attached trailers or business vehicles (you’ll need commercial auto in this case)
- Heavy machinery like tractors or bulldozers
- Damage from misuse, negligence, or natural disasters
Note: This coverage is designed for tools and equipment that travel with you, not items permanently installed in one location.
💡 Insurance Term To Know: Inland Marine Insurance
Trailer and equipment insurance is usually written into your policy as “inland marine insurance.” While the name’s origins stem from items overseas travel, it now refers to coverage for any movable tools or equipment used for your business. Inland marine is one of the most common coverages needed by small businesses.
What General Liability and Lawn Care Equipment Covers
Here’s a quick side-by-side look at general liability vs. trailer and equipment insurance, and what each one covers:
| Incident | General Liability Insurance | Trailer and Equipment Insurance |
|---|---|---|
| Customer gets injured on the job site | ✅ | ❌ |
| Weed trimmer is stolen from your trailer | ❌ | ✅ |
| A rock kicks up from a mower and breaks a client’s window | ✅ | ❌ |
| Mower catches fire in the garage | ❌ | ✅ |
| Legal costs from a lawsuit | ✅ | ❌ |
Pro tip: Insurance policies vary, so review your terms and exclusions carefully. Explore your options further with our lawn care insurance guide.
General Liability vs Lawn Care Equipment Insurance: Which Coverage Do You Really Need?
Probably both. Since no two lawn care businesses are alike, your lawn care insurance should reflect your specific risks and budget. Naturally, your insurance costs will change as your business grows.
Here are some quick questions to help you assess what type of coverage you need:
- Do you work on customer property? If yes, you need general liability.
- Do you rely on tools, trailers, or machines to do your work? If yes, you need trailer and equipment insurance.
- Have landscaping clients ever asked you for a Certificate of Insurance (COI)? If yes, you need general liability.
- Could losing your equipment tomorrow stop you from earning income? If yes, you need trailer and equipment insurance.
And revisit these as you grow. More jobs and tools mean bigger risks, and outdated policies can leave you underinsured. A quick insurance check-in once a year can save a huge headache later.

Real-World Examples of Lawn Care Insurance Claims (These Actually Happen!)
Lawn care insurance is what saves your business when the unexpected happens. These are the types of claims we see all the time:
Flying rock, broken window
- You’re mowing a yard when a rock shoots out, shattering the customer’s sliding glass door.
- What saves you? General liability insurance can help cover the cost of repair.
Trailer theft at lunch
- During a job you grab a quick lunch and come back to find your blower is gone from the trailer.
- What saves you? Lawn care equipment insurance can help replace stolen gear, and even cover the cost of waiting for the replacement.
Client trips over equipment
- A hose is left unattended over the path to the front door, causing the client to trip and break their wrist.
- What saves you? General liability insurance can help you pay for the client’s medical bills and lost wages while they’re recovering and unable to work.
Fire Damage
- A spark ignites stored gas in the garage where your tools, trailer, and heavy equipment are kept, causing everything in the space to be irreparably damaged.
- What saves you? Lawn equipment insurance can cover the hefty cost of replacing your whole arsenal of tools at the same time.’
These aren’t freak accidents. They’re everyday risks in lawn care. With the right landscaping insurance, you can save money, time, and stress.
Protect Your Gear and Your Business — Get Covered Today!
Accidents and theft don’t wait for a convenient time. One day you’re landscaping, the next you’re dealing with a knocked-over statue or a missing mower. The right insurance doesn’t just protect you, it keeps your entire business moving forward.
Insurance Canopy designs coverage specifically for lawn care pros, so you get the protection you actually need without paying for what you don’t. This is why so many landscaping professionals choose Insurance Canopy for tailored coverage.
FAQs About General Liability vs Lawn Care Equipment Insurance
Is General Liability Enough for a Lawn Care Business?
General liability helps protect you from third-party claims of injury or property damage, and is an excellent starting point for a lawn care business, but it’s not enough to cover everything.
For example, general liability coverage won’t help if your equipment is stolen or damaged. You’ll need to add trailer and equipment insurance (inland marine insurance) to fill that gap in coverage.
Do I Need General Liability and Equipment Insurance?
If you work on customer property and rely on expensive tools, yes, you’ll need general liability and equipment insurance to cover your business. It saves you from paying thousands out of pocket should an accident occur that causes injury, property damage, equipment theft or equipment damage.
What’s the Best Insurance Bundle for Landscapers?
Most landscapers choose a Commercial General Liability (CGL) bundle that combines general liability with trailer and equipment coverage, and more.
Insurance Canopy makes it simple to add equipment protection — either when you first purchase your policy or later through your customer dashboard.
Can You Put Insurance on a Lawn Mower?
Yes, lawn care business owners can insure their tools and other movable equipment with trailer and equipment insurance under an Insurance Canopy policy.
Are Lawn Mowers Covered Under Homeowners Insurance?
Yes, lawn mowers are commonly covered under a homeowner policy — but only for personal use. If you own a lawn care business, then incidents involving your mower are not covered as it’s then considered business property.
This is where it’s important to have both general liability insurance and trailer and equipment coverage to protect your lawn care or landscaping business.
What Kind of Insurance Does a Lawn Care Business Need?
Lawn care business owners should acquire general liability insurance and trailer and equipment coverage (inland marine). The former will help cover you in case an incident causes injury or property damage to a customer or bystander, and the latter can help cover the cost to repair or replace your movable equipment if it is stolen or damaged.
How Do I Cover My Lawn Care Equipment?
You can purchase trailer and equipment coverage as an optional add-on to a lawn care general liability policy through Insurance Canopy.