
Gardening Insurance Cost
Understanding your gardening business insurance costs makes it easier to plan your budget and protect your livelihood from accidents, equipment loss, or lawsuits. Insurance Canopy offers affordable, customizable coverage options designed specifically for gardeners, so you get the protection you need to protect and grow your business.
How Much Does Gardening Insurance Cost?
Gardening insurance with Insurance Canopy starts at $33.75 per month or $375 per year. Compared to the industry average ($1,000+ per year), Insurance Canopy is one of the most competitive plans on the market — so you can spend more of your hard-earned revenue on scaling your business, not insurance premiums.

What Types of Payment Plans Are Available?
Insurance Canopy offers flexible payment options, including monthly or annual plans. Choose the one that best fits your budget and calendar.
Monthly payments are best for lawn care pros who need lower prices now. Rather than paying all at once, you can break your premium into installments. You may also prefer month-to-month coverage if your work is seasonal.
Annual payments are ideal for landscapers who value long-term savings and want to enjoy 365 days of peace of mind.
Monthly payments:
✔️ Base policy amounts to a total of $405 for the year
✔️ Pay your insurance premium in monthly installments
✔️ Ideal for businesses with tighter cash flow
Annual payments:
✔️ Base policy equivalent to $31.25/month when paid annually
✔️ Save up to 7.5% with one upfront payment
How Much Does Each Type of Coverage Cost?
General Liability Insurance: Starting at $33.75/Month or $375/Year (Higher Limits Available)
This coverage can protect you from paying out of pocket for harm or damage you unintentionally cause others. This includes things like client or non-employee slip-and-fall injuries and damage to client property.
Insurance Canopy’s general liability gardening policies all come with:
- General Liability coverage
- Products & Completed Operations coverage
- Personal & Advertising Injury overage
- Damage to Rented Premises coverage
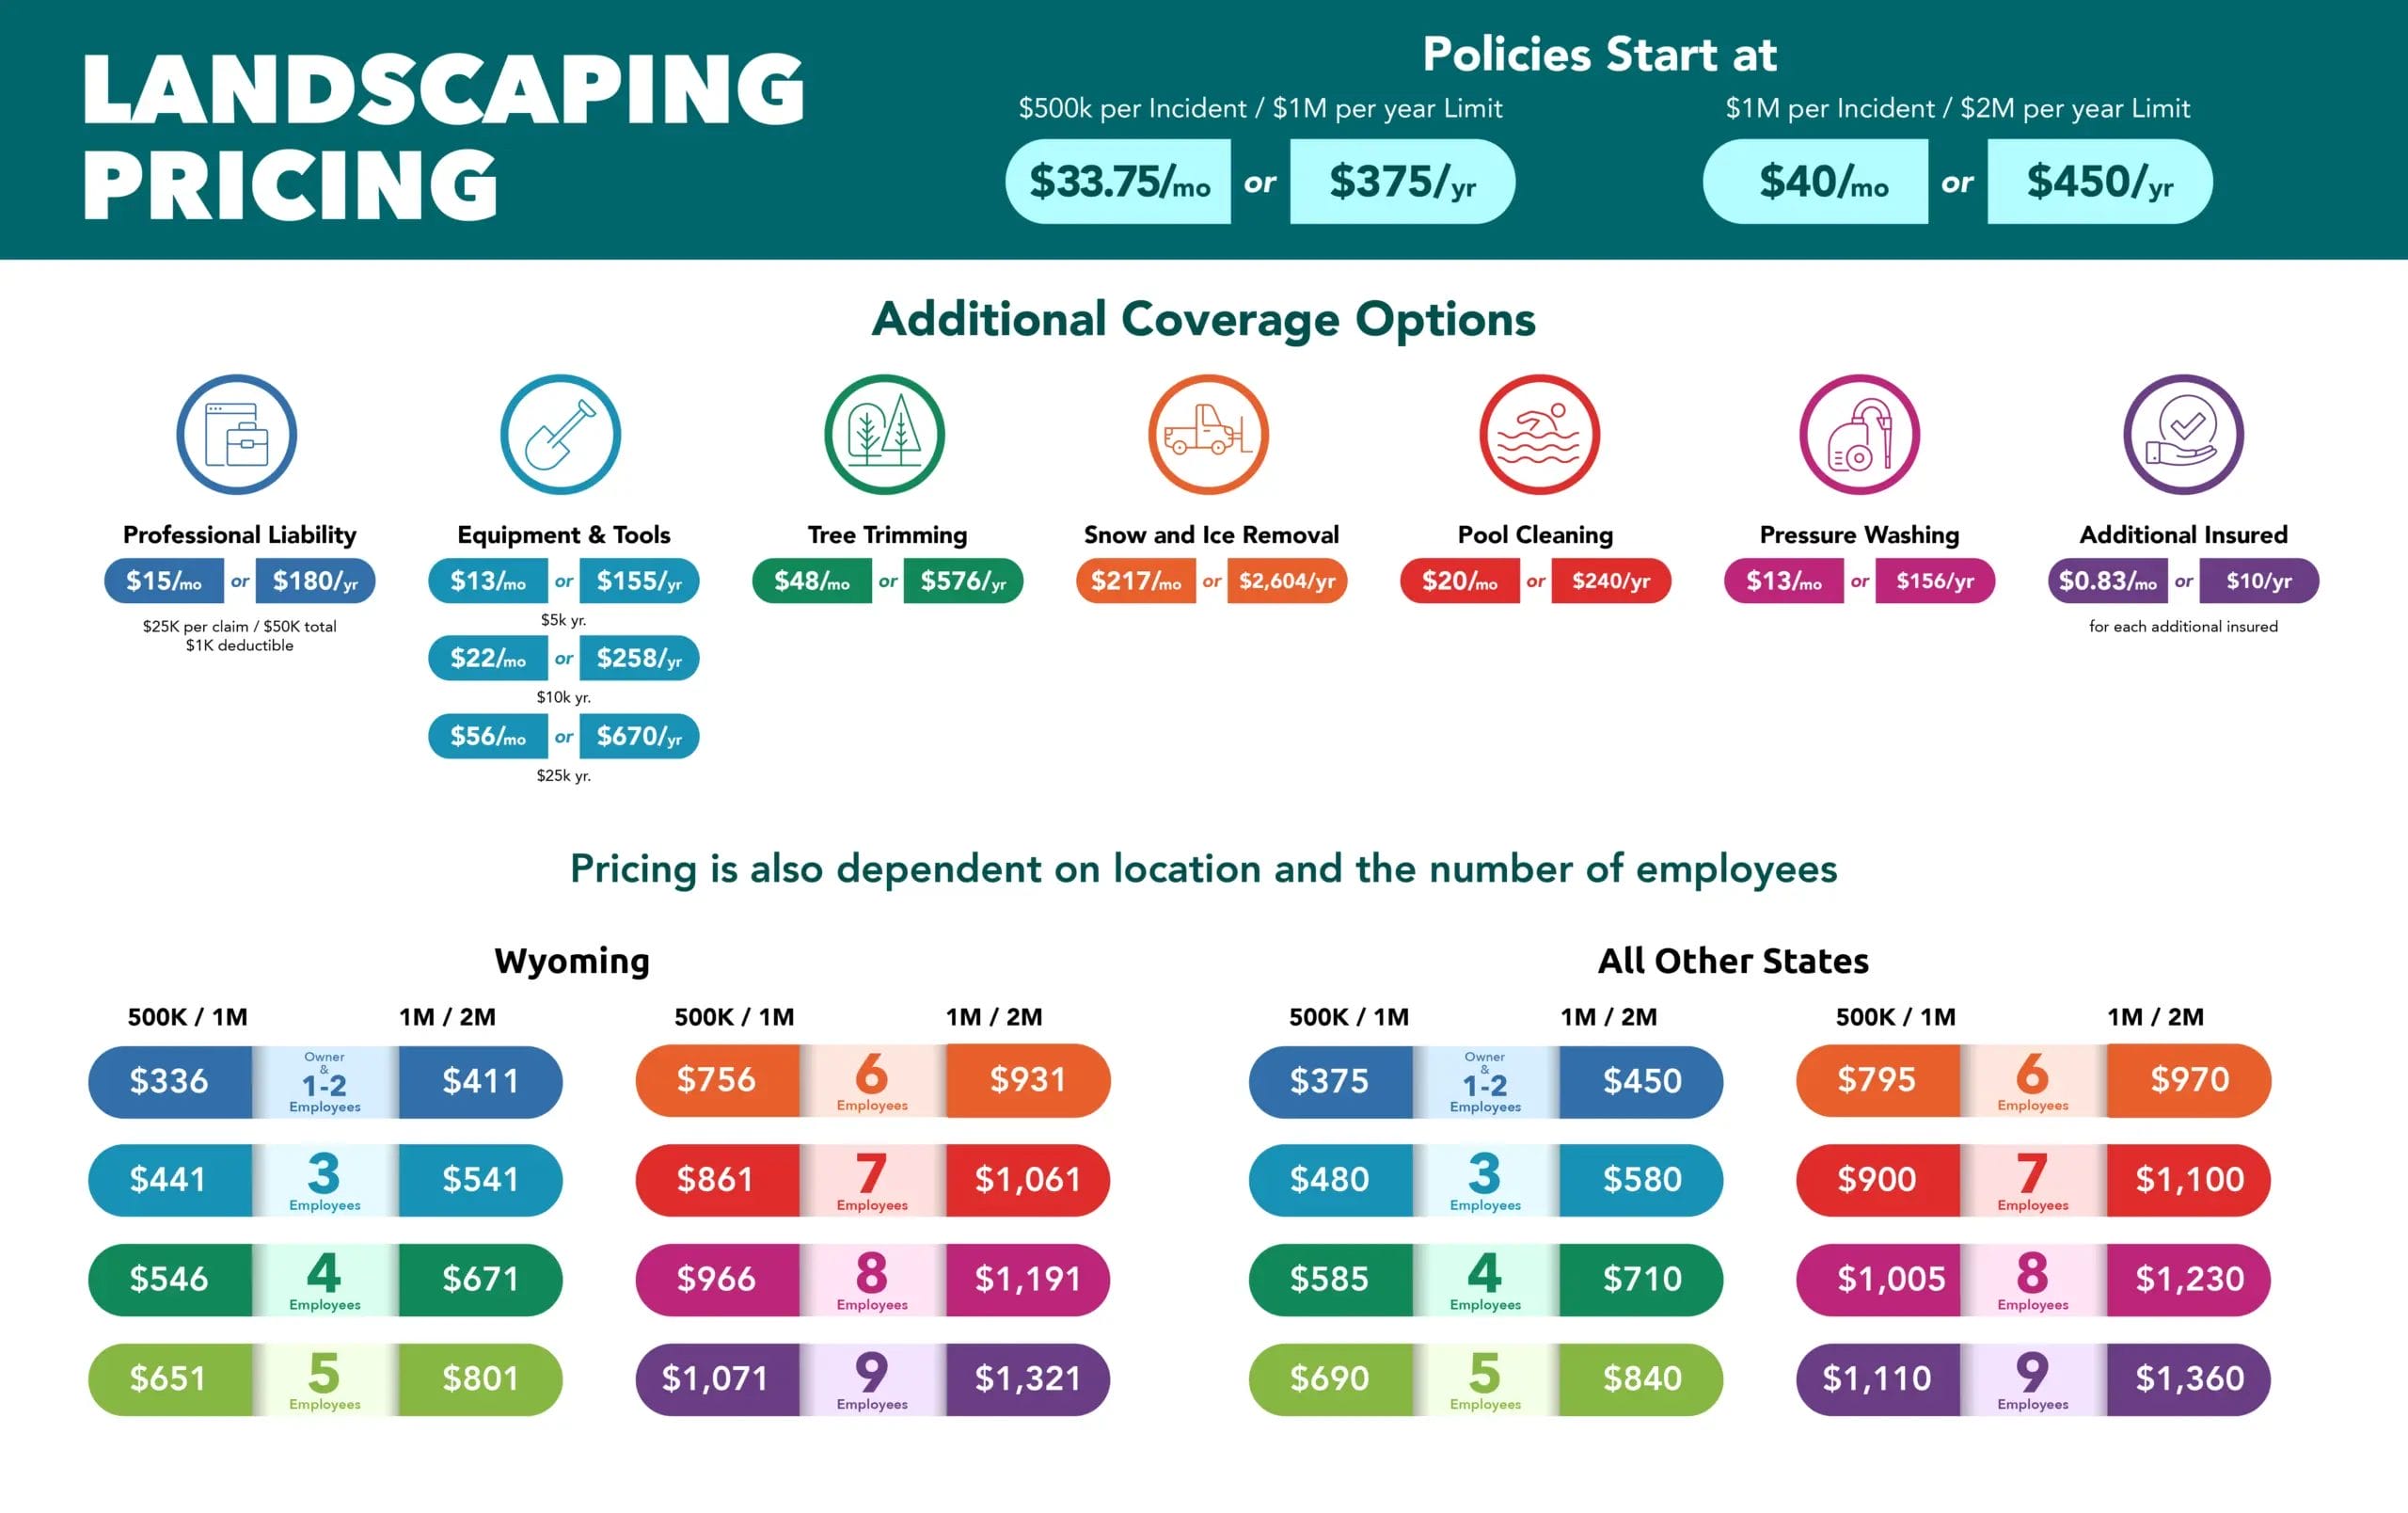
Policies that include limits of $500,000 per incident (occurrence) and $1 million total (aggregate) start at $33.75/month or $375/year. Higher-limit policies that include $1 million per incident and $2 million aggregate coverage start at $40/month or $450/year.
Equipment and Tools (Inland Marine) Coverage: +$13 – $56/Month
This optional coverage can help you pay to repair or replace your business gear in case of theft or damage. Also known as inland marine insurance, it’s designed to cover the portable tools and equipment you use, like lawnmowers, shears, and even laptops.
This coverage does not apply to vehicles, trailers, wear-and-tear damage, or mysterious disappearances.
There are three tiers of tools coverage, and all include a $500 deductible:
- Tier 1: $5,000 limit for $13/month or $155/year
- Tier 2: $10,000 limit for $22/month or $258/year
- Tier 3: $25,000 limit for $56/month or $670/year
Professional Liability Coverage: +$15/Month or $180/Year
Professional Liability, also known as errors and omissions coverage, is an optional coverage designed to protect business owners against financial losses arising from errors, mistakes, omissions, or negligence in their professional services.
Coverage limits for this professional liability add-on are $25,000 per occurrence and $50,000 aggregate, with a $1,000 deductible.
Cyber Liability Insurance: +$8.25 – $12.50/Month
If you store client contact details digitally, take bookings through your website, or accept digital payments for your services, you could be a target of cybercriminals. Cyber liability insurance is designed to protect you from the financial fallout by covering things like:
- Forensic fees
- Legal fees if affected clients sue you
- Recovering and restoring data and systems
- Data breach notifications if your booking system is hacked
- Ransomware or cyber extortion demands payment to unlock your files
- Business interruption expenses if your website or payment system goes down
There are two coverage tiers for cyber liability, and both include a $1,000 deductible.
Tree Trimming: +$48/Month or $576/Year
Tree trimming liability insurance is an optional coverage that expands your existing gardening insurance policy. It’s designed to cover third-party claims related to tree work, like if a trimmed tree limb falls on a customer’s car or a pedestrian gets hurt tripping over a pile of cut branches.
This add-on covers pruning, cutting, and shaping shrubs and trees up to 30 feet. However, it excludes removals, stump grinding, arborist work, and tree trimming within 15ft of power lines.
Snow and Ice Removal: +$217/Month or $2,604/Year
Designed for lawn care businesses that perform residential snow removal services, snow and ice removal insurance coverage is built to cover snow removal around single-family homes, driveways, and small multi-family complexes.
Services for commercial properties and public roads are not covered under this endorsement.
Pool and Pond Maintenance: +$20/Month or $240/Year
This coverage is intended to cover pool cleaning, chemical treatments, and basic pump and filter repairs. It can also help protect you from expensive claims if you or an employee accidentally damages a client’s pool or pool equipment during service.
Pressure Washing: +$13/Month or $156/Year
This coverage protects gardeners and other landscaping businesses that may provide power washing services for residential driveways, fences, patios, and exterior walls. However, you must only clean surfaces less than two stories tall and use non-toxic, water-based chemicals.
Additional Insureds: +$0.83/Month or $10/Year
For some gardening jobs, you need to add clients, property managers, or contractors to your liability policy. When you add an additional insured to your gardening policy, you extend certain protections to that party, so they can receive coverage if they’re named in a claim or lawsuit because of your work.
Most botanical gardens, homeowners associations (HOA), and commercial properties require you to add them as an additional insured before doing on-site gardening work. With Insurance Canopy, you can add additional insureds at any time from your customer dashboard.
Each additional insured costs $10 per year.
Workers Compensation: Rates Vary
If you have employees and someone on your team gets hurt on the job, workers compensation is designed to pay for their medical care and replace some of their lost wages while they recover.
This is an optional add-on coverage, but because workers compensation laws differ from state to state (and most states require it even if you have only one employee), your coverage limits and costs depend on your state’s specific requirements.
Commercial Auto Insurance: Rates Vary
Your personal car insurance typically won’t cover accidents or damage that occur while you’re using your regular vehicle for work purposes. So, if you use a vehicle to do things like haul supplies, transport flower flats and tools, or do other work tasks, you need commercial auto insurance.
Commercial auto coverage is an optional add-on and applies to:
- Legal expenses if you’re sued
- Repairs to your work vehicle after an accident
- Repairs to others’ property damaged in an accident
- Medical costs if other people (not employees) get hurt
Each state has its own auto insurance regulations and standards, so your coverage limits and costs will vary from state to state.
Landscaping Bonds: Rates Vary
Some clients or local governments may require you to be bonded before you can start work. A gardening bond is like a promise that you’ll finish the job as agreed and follow any rules or regulations.
If something goes wrong and a claim is filed, the bond company pays the client, but your business will need to pay the bond company back. Common types of gardening bonds include:
- License and permit bonds: Some states or towns require these to make sure your gardening business follows local laws and regulations
- Contractor bonds: Helps protect your clients if a landscaping or planting job isn’t finished the way you promised
- Business service bonds: Can cover employee theft if one of your employees steals tools, plants, or money while working on a client’s property
Bond rates vary, but are often 1% to 15% of the total bond amount.

Still have questions regarding our policies? Feel free to reach out to our licensed insurance agents. We are available Monday through Friday from 8am–8pm ET.
What Factors Affect Gardening Liability Insurance Cost?
Liability Limits
Higher base general liability limits mean higher starting premium costs.
Business Size
More employees mean more potential for workplace injuries, which increases your workers compensation and liability costs.
Optional Coverages & Services Offered
Offering additional services, like tree trimming or snow and ice removal, requires additional coverage. Adding optional coverages increases your premium cost, but strengthens your base policy.
Gardening Liability Insurance Cost Factors
Your gardening insurance policy cost will ultimately depend on a variety of factors, including:
- Your state
- Your liability limits
- Your claims history
- The types of services you offer
- How many employees you have
- Which types and tiers of optional coverages you add on
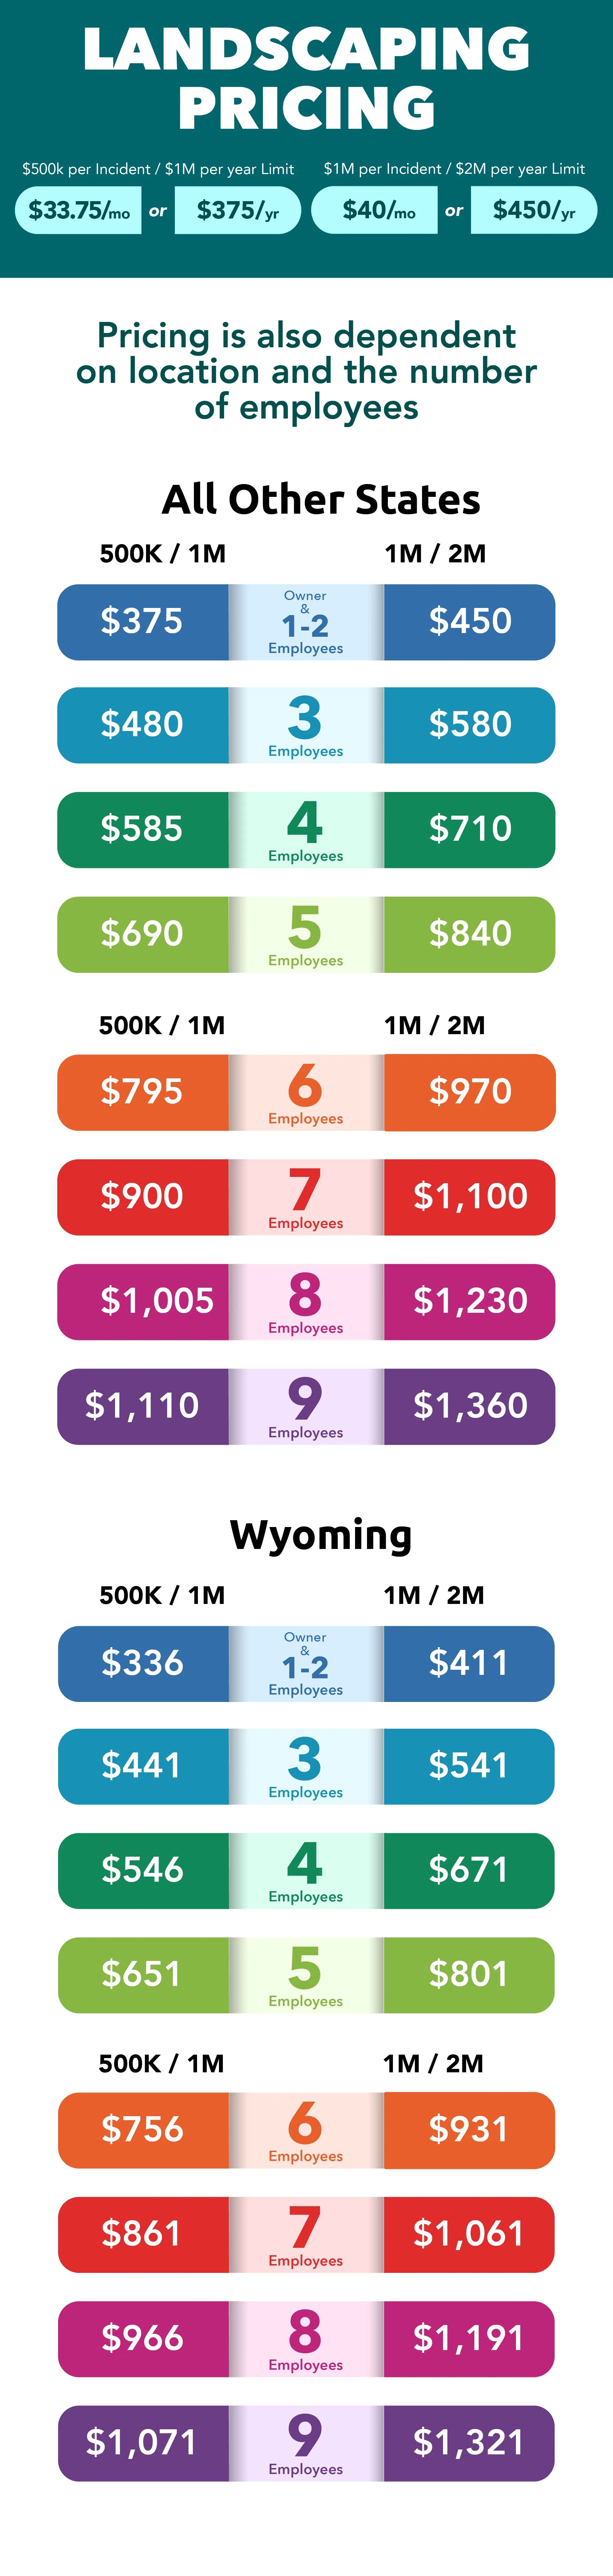
Here’s a breakdown of how your state and number of employees affect your base liability insurance costs:
How Can I Reduce the Cost of Gardening Insurance?
An easy way to lower your gardening business insurance costs is to choose annual billing over monthly payments.
You can also mitigate your costs by using these risk management strategies to limit your on-the-job risks:
- Give your shears, trimmers, and other tools a once-over before you start working to verify they’re in good shape and to prevent accidents.
- Conduct regular safety checks for tripping hazards on walkways, and keep an eye out for other preventable accidents.
- Work within the scope of your policy and add-on coverages. This means avoiding work that is specifically excluded from coverage, like trimming trees within 15 ft of a power line.
Why Insurance Canopy for Gardening Insurance?
Need a no-nonsense gardening business insurance policy that meets you where you work? We’ve got you covered, rain or shine:
- Coverage that Scales with Your Crew Size
- Affordable Monthly or Annual Payments
- Instant Certificate of Insurance (COI)
- Manage Your Policy Online 24/7

Gardening Insurance Coverage Details
General Aggregate
The most your policy will pay in a 12-month policy period for bodily injury and property damage claims that you become legally obligated to pay due to your business services.
$2,000,000
Products & Completed Operations Aggregate
The maximum amount your policy will pay in a 12-month period for bodily injury and property damage claims that result from the products you use to perform your services. However, it does not cover products that are sold or distributed.
$2,000,000
Each Occurrence Limit
The maximum your policy will pay for a bodily injury or property damage claim that you are legally obligated to pay due to your business services.
$1,000,000
Personal & Advertising Injury Limit
The amount that your policy will pay for claims arising out of one or more of the following offenses:
- False arrest, detention, or imprisonment
- Malicious prosecution
- Wrongful eviction or wrongful entry
- Oral or written publications that slander or libel a person or organization
- Oral or written publication or material that violates a person’s right of privacy
- The use of another’s advertising idea in your advertisement
$1,000,000
Damage to Rented Premises Limit
Applies to damage by fire to premises rented to the insured and to damage regardless of cause to premises (including contents) occupied by the insured for 7 days or less.
$100,000
Equipment & Tools Coverage (Inland Marine)
Also known as “inland marine,” Equipment & Tools covers moveable property like mowers, edgers, and gardening supplies. Excludes any structures and items that are permanently fixed to a single location.
$155/yr.
$258/yr.
$670/yr.
Lawn Care Professional Liability
Also known as errors and omissions (E&O), this coverage protects you from financial losses resulting from mistakes or negligence in your services. This includes advice or consultation you offer to a customer that causes bodily or financial injury.
$25K per claim up to $50K total
$1K deductible
$15/mo or $180/yr.
Snow and Ice Removal
Liability coverage for lawn care businesses that perform residential snow removal services. This covers single-family homes, driveways, and small multi-family complexes. Services for commercial properties and public roads are not protected under Snow and Ice Removal coverage.
$217/mo. or $2,604/yr.
Pool and Pond Maintenance
Covers pool cleaning, chemical treatments, and basic pump and filter repairs. Pool and Pond Maintenance also protects you from expensive claims if you or an employee accidentally damages a client’s pool or equipment during service.
$20/mo. or $240/yr.
Pressure Washing
Protects landscaping businesses that service residential driveways, fences, patios, and exterior walls. However, the business must only use non-toxic, water-based chemicals and clean surfaces less than two stories tall.
$13/mo. or $156/yr.
Tree Trimming
Designed to cover pruning, cutting, and shaping shrubs and trees up to 30 feet (with endorsement). However, it excludes tree removals, stump grinding, arborist work, and tree trimming within 15ft of power lines.
$48/mo. or $575/yr.
Additional Insureds
Some lawn care jobs require temporarily adding contractors or clients to your policy as additional insureds. Pricing starts at just $0.83 per month, or $10 per year per insured. Also, if you use independent contractors to assist with jobs, the coverage requires that you are listed as an additional insured on their policy.
$0.83/mo. or $10/yr. (each additional insured)
Workers Compensation
Provides financial compensation for employees who suffer work-related illnesses or injuries, including lost wages, medical expenses, and rehabilitation. It also covers your legal fees if an employee sues you over a workplace injury or illness.
Surety Bonds
Bonds protect your clients from financial loss if you are unable to complete a contract. They also ensure you meet all legal requirements necessary for jobs.
Cyber Liability
Protects your business from financial loss caused by phishing scams, ransomware, and other cyberattacks. If your company processes payments and stores client information digitally, cyber liability is an essential part of securing your business.
Commercial Auto Coverage
Lawn care professionals typically rely on a fleet of vehicles to transport landscaping equipment and crew members. If an employee gets into an accident on the way to a job site, commercial auto coverage can cover third-party injuries and damages. Additionally, it also covers vandalism and theft of your equipment.
How Do I Get a Quote?
Complete our quick online application and get your free quote in minutes. Just tell us a little about your business and what coverage options you need, and we’ll handle the rest. You’ve got flowers to plant and jobs to finish — get covered without losing half the workday.
Common Questions About Gardening Business Insurance Costs
Is Gardening Insurance Required?
Gardening insurance may be required based on your state, city, or client contracts. Many HOAs, botanical gardens, and commercial properties require proof of insurance before they’ll hire you.
Does Gardening Insurance Cover Stolen Equipment?
Your standard gardening policy does not cover stolen equipment. You need to add tools and equipment coverage to protect your gear from theft or damage. This optional coverage helps pay for repairs or replacements if your tools are stolen or damaged.
Keep in mind that for theft claims, you typically need a police report.
Can I Get Insured if I’m a Part-Time Gardener?
Yes, you can (and should!) get insured if you’re a part-time gardener, because part-time work still comes with risks. Even one mishap could turn into a claim that costs more than a year’s worth of insurance premiums.
Insurance Canopy offers coverage for seasonal, part-time, and full-time gardening businesses, so you can stay protected no matter your schedule.
What Does Gardening Insurance Typically Cover?
General liability insurance for gardeners is designed to cover third-party injury and property damage claims and related legal costs, like unintentionally breaking a customer’s sprinkler system or a passerby tripping over your tools.
From there, you can customize your policy with add-ons like equipment protection, workers comp, commercial auto, cyber liability, or additional insureds – giving you the flexibility to match your coverage to how you work.
Still have questions regarding our policies? Feel free to reach out to our licensed insurance agents. We are available Monday through Friday from 8am–8pm ET.
JoAnne Hammer | Program Manager
JoAnne Hammer is the Program Manager for Insurance Canopy. She has held the prestigious Certified Insurance Counselor (CIC) designation since July 2004.
JoAnne understands that starting and operating a business takes a tremendous amount of time, dedication, and financial resources. She believes that insurance is the single best way to protect your investment, business, and personal assets.
JoAnne Hammer is the Program Manager for Insurance Canopy. She has held the prestigious Certified Insurance Counselor (CIC) designation since July 2004.
JoAnne understands that starting and operating a business takes a tremendous amount of time, dedication, and financial resources. She believes that insurance is the single best way to protect your investment, business, and personal assets.